
Recently, when I was changing banks, I applied for a credit card, and was surprised to hear after a week’s delay that it was declined due to financial misconduct. This is after decades of paying accounts on time, paying my credit card in full every month, etc. So I was pretty surprised, and I had absolutely no idea why this could be.
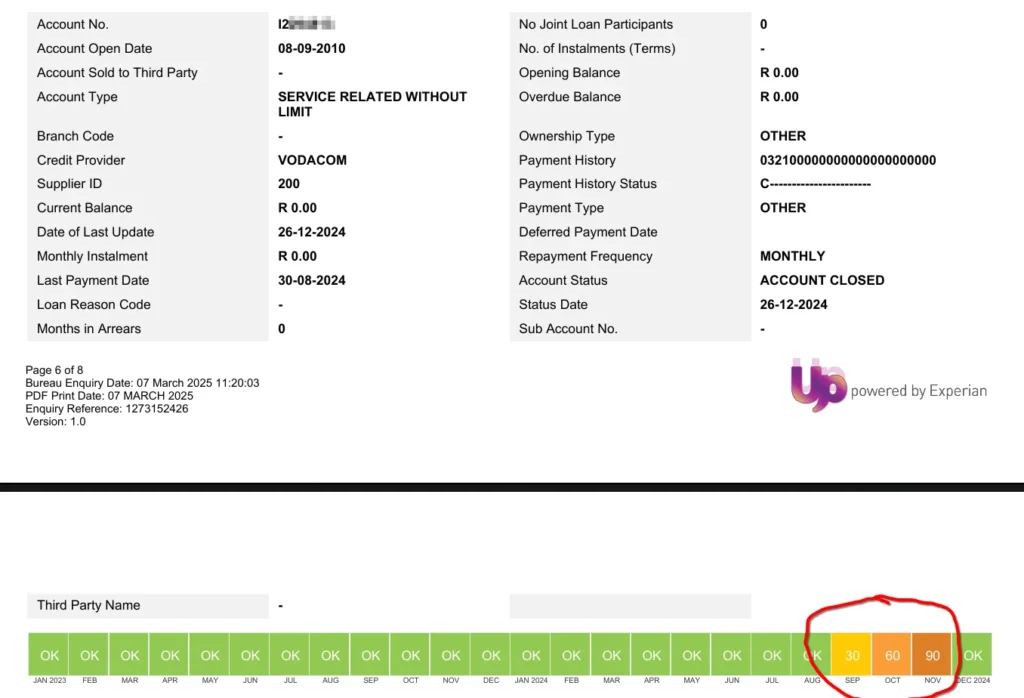
This post is a warning to others to check your credit report every now and again, especially after you have closed accounts somewhere. The problem is, neither the company reporting you (in my case Vodacom) seems to be legally obliged to inform you they are reporting you, and it also seems Experian does no checking at all either. So you as the consumer have no idea this is happening behind your back. In my case with Vodacom, I also received no further statements or even warnings at all from Vodacom that I had any outstanding debt after closing my account. In fact, I still don’t know what the amount is. I had a debit order with them for about R112 per month for a data SIM, that they managed, to collect the money monthly. I have my last statement and confirmation of the debit order going off after that to settle that account. Luckily I recorded all my phone calls with Vodacom, and they did tell me if there was anything outstanding after closure, they would contact me after about 7 or 8 days. That contact most definitely never happened in any form whatsoever.
Most consumers would expect that if they received their last statement a few days before the account closure, and then saw the SMS from the bank showing the debit order went off at the start of the following month (after account closure), that the account has been paid.
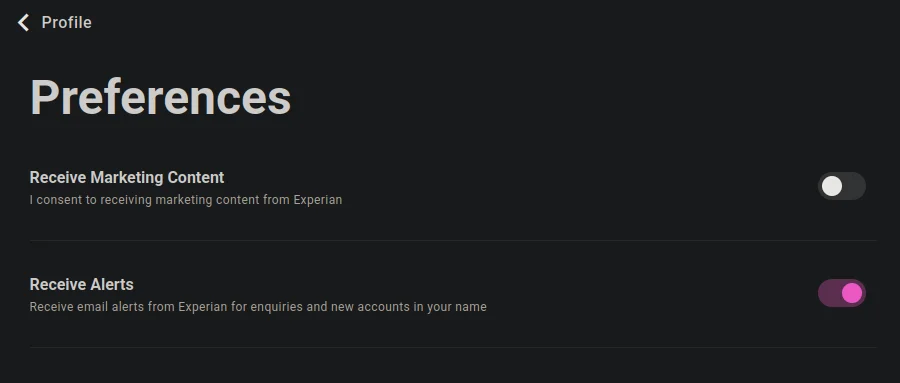
After lots of digging around, I discovered the bank get its information from Experian, which is an international credit bureau. Now, the good thing is anyone can go draw their credit report themselves at https://www.experian.co.za/consumer, and your RICA’d mobile phone number is used to verify you against your ID. You can also set up alerts to notify you of activity on your profile. However, this does not look like it includes any bad debt reports made against you.
This is what my report looked like for Vodacom (they list a few places where you have accounts or credit of any form.
According to Experian’s website, this is what they are about: “Our world is built on data. It’s all around us, growing in power and influence every day. We work to turn that data into something meaningful. We gather, analyse, combine and process it to help people and organisations achieve their goals – whether that means planning for a secure future or getting to know your customers better. We believe data has the power to change lives. By helping people and organisations make the most of their data, we can make a positive difference to our society and communities.”
But in this particular case, the actual blame does not lie with Experian (with regard to the lack of notification) as the whole issue was instituted by Vodacom. That said, Experian has still not responded to my formal dispute lodged with them on 14 April 2025, except to provide an automated reference number.
In Vodacom’s case, this is NOT an isolated incident, and my opinion is there is something seriously wrong with the account closure process. But seeing it has been happening over many years and the complaints are very similar, this behaviour is bordering on reckless and negligent.
See https://www.hellopeter.com/vodacom/reviews/urgent-complaint-regarding-negative-impact-on-my-credit-score-due-to-vodacom-5685392 – Vodacom did not notify the customer of outstanding amounts.
Also, https://mybroadband.co.za/forum/threads/vodacom-multiple-missed-payments-affecting-my-credit-score-im-on-prepaid.1097032/ – customer had outstanding balance after account cancellation (others said here they had similar experiences with Vodacom).
Also, https://mybroadband.co.za/forum/threads/vodacom-testing-my-patience-resolved.404411/ – with regard to 7-year-old debt that Vodacom had not informed the customer about.
So, the common denominators often seem to be this happens with account closures, and customers are unaware of the debt as well as any escalation to Experian.
In my case this has cost me a lot of time, lengthy phone calls to Vodacom, and also struggling to get a response from the Legal Collections department. I did finally get a response from them on 14 April 2025 that stated: “The ITC update escalation was sent and updated”. I had to again follow up to find out what an ITC update is, and this was their response: “Kindly note ITC update means we have sent the update to credit bureaus.” No apology at all, nor explanation of what happened and why I was listed with the credit bureaus. I did ask them on 14 April 2025 that this situation warrants an investigation on their part, but there was no reply to that suggestion.
The issue is still not finalised as my bad report still stands at Experian as of today, so I will need to follow up further now with Vodacom. I have also requested from Experian for a copy of exactly what was sent to them as evidence of my having outstanding debt, as well as follow-ups sent by Vodacom to myself requesting payment.
Many may be thinking, so what about a credit report, it is something in the background that does not affect me. Well bear in mind firstly when I switched banks my credit card was declined. Secondly, all banks base the cost of your banking and credit upon your credit risk. Any car you buy, house you want to buy, and loan you want to take out, and flat you want to rent, is going to have a slightly higher interest rate to cover the risk. I won’t say who my new bank is, but they were open enough to share the report with me, which alerted me to this situation. They also could inform me of every account I opened over the past 20 plus years, including a home mortgage back in 1999 with a bank that has long ceased to exist. Bank’s memories don’t get wiped clean after 3 or 5 years. They look at everything you have done as far back as your records stretch.
In summary, though, I do hope this experience is a wake-up call to others to be wary around account closures and assumptions made. It is extremely unfair that consumers have to bear the time and cost to sort out issues that have been instigated by big corporations, who seem to be oblivious of what their various departments are doing (or just don’t care):
* After any account closure, check your credit report about 3 to 4 months later.
* Do not delay doing this, as 5 or 10 years later you may not still have all the evidence and records you need.
* Make sure you ALWAYS record phone calls with companies which do business over the phone (twice before I’ve had to reverse contract changes with Vodacom, and these recordings saved me). If you don’t have an app like Call Recorder Pro, just put the speakerphone on and use any audio recording app. LOL just remember when you are given that recorded message that the corporation is recording the call for quality and training purposes, always shout back “and so am I!”.
* Do 6-monthly or annual credit report checks.
* Set alerts on your Experian profile.
* If you require assistance, remember there are various Ombuds in South Africa, including the Credit Ombud regarding the Code of Conduct followed by credit bureaus and credit providers. They are there to assist consumers, and I’ve never lost a case that I’ve taken to them. Consider the Ombud to be your free legal council, but make sure you have done all your preliminary steps first. More are listed at https://iol.co.za/personal-finance/my-money/2022-12-09-six-ombuds-you-can-turn-to-for-help/.
* Use sites like Hello Peter at https://www.hellopeter.com/ as you’ll quickly see you are far from alone in experiencing issues with a deaf corporation. It’s important that consumers make their voices heard.