
I thought I’d tell this story, as when it dawned on me, I found quite a few others complaining online that their credit records were ruined after closing their accounts at Vodacom. I pushed back against my treatment and got my record cleared with the help of the National Financial Ombud Scheme (NFO). I also “eventually” got to understand what happened, but not really why, and I’ll publish Vodacom’s response after my pushing for an apology, which I never received.
This is not my first run in with Vodacom at all, but at least on one of the previous occasions I did receive a written apology, but that matter did also add to issues resulting in me ending my business with Vodacom, but that is a story for another rainy day.
Like many others who have closed accounts at Vodacom, I was completely unaware that any serious issues had been looming over the months after I closed my account effective at the end of August 2024. As a matter of course, I do keep audio recordings (and SMSs) of all my interactions with company helpdesks, especially those which insist on doing everything telephonically, and who record the calls for “quality and training purposes”. In fact, in the previous case I alluded to, Vodacom could not find that recording, but it was only after I sent them my audio recording (also prepended with the shout-out “I’m recording this for quality and training purposes”) that the matter was speedily resolved. So a lesson to consumers, you need to record all your calls, as those corporate recordings are NOT there to protect you the consumer (a bit like HR in any corporate is not there for the employees).
But where was I…. Oh yes, blissfully unaware my financial ruin was about to hit me, I changed banks in February 2025 (as many do, to get better deals). This should have been a walk in the park as my home is paid for, my car paid for, all accounts are settled within 30 days including my credit cards, etc. I’ve had a spotless credit record for over 40 years. So I was a bit surprised when I was just not getting a credit card issued by the new bank. I was getting excuses, and eventually I started escalating and pushing for the issue to get finalised, as I wanted to close my accounts at my old bank.
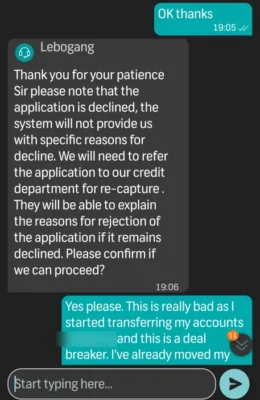
So imagine my utter disbelief and surprise when the new bank sent the following part of a screenshot on 7 March 2025 to show I have a bad credit record for not having paid an account for over 3 months and was flagged for financial misconduct!
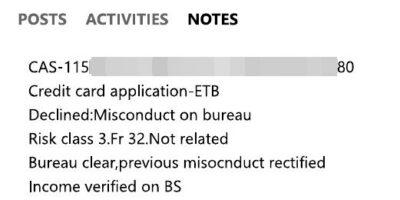
I was totally dumbstruck and actually went into shock as I thought it must be identity fraud or something. I went into Experian’s website to draw my credit report and saw the following for the Vodacom account:
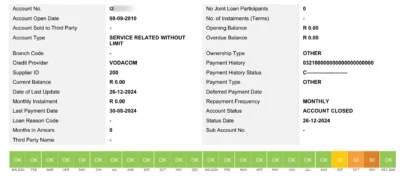
What the above report showed was that Vodacom had reported me for not paying my Vodacom account for 3 months (the yellow progressing to dark orange blocks). But the fact was I had closed my account at the end of August and I had an SMS notification saying my final statement was settled for the correct amount. Remember that Vodacom manages the debit order off my current account, so they executed that debit order, and they in fact stopped it after closure. So Vodacom managed the payments. Yes, and I was a customer with Vodacom for 15 years with an account paid in full at the end of every month.
And so began my long battle of back and forth with Vodacom’s Legal Collections Department… I presented my proof of account closure with 30 days notice (did I mention I had to submit it a second time, as the first time I got no confirmation from Vodacom?):
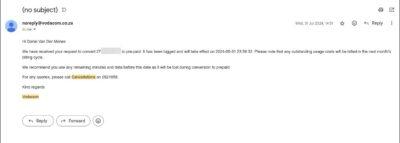
So based on the above, one would expect then that the August statement must be paid in full by the end of August. I had stopped using the data SIM by the end of July, so all that should be owed was the monthly fixed charge. My monthly charge was R121.67
Below is a copy of the usual SMS confirmation I got at the end of very month, showing my debit order had indeed gone off at the end of August 2024 (the date my account was closed). I was told when i closed the account at end f July, the final paymnet would be end of August (30 days notice).

Which brings me to another issue with many companies. Vodacom sends out a monthly “account statement” but although it states “invoice and statement are attached for your convenience” they in fact are not attached, so there is no convenience at all. There is a link to log in and then you have to download the statements. Try this monthly for a number of different accounts, and you end up not logging into every account, every single month. Also, after your account is closed, you have lost access to all those statements and accounts immediately. My account was a for a fixed amount of data every month, so I would just watch out for any exceptions to the amount debited, and I’d watch that my usage stayed under the allocated data amount.
So yes, I rely on the monthly SMSs to show that the amount goes off at the end of the month. At the end of August 2024, I saw the usual amount going off, meaning the final account should have been paid (as Vodacom was also managing the debit order). With the account now closed, of course I cannot actually log into the account any more either.
And so my interactions with Vodacom’s Legal Collections department started on 18 March 2025 with me phoning and speaking to the Department (I have the lady’s name, recordings, etc) and I was assured the issue would be dealt with, and I’d be called back “within 3 to 7 days”. After 8 business days, I was not called back, and so began the escalations from my side. Despite Vodacom Legal Collections assuring me they would sort it out with the credit bureaus, absolutely nothing changed. I had also asked in writing from Vodacom what the basis was for the reporting to the credit bureau. I was trying to understand what the debt was for and how much it was. I never received any reply about that at all. It was costing me phone calls, repeated authentications on my side, and Vodacom only saying they had sent it to the credit bureau for correction and I must allow another 7 days.
Eventually on 14 April 2025 I escalated the issue to Experian themselves, after all they had published the adverse report, so surely they must have received some evidence? Well, Experian gives an auto-reply stating you must log a dispute for this type of issue. So I logged a dispute with Experian, and despite an automated acknowledgement saying I must still receive an actual dispute reference number, I never got any further responses from Experian, even after I sent follow-ups to them. So basically Experian just plain ignored me as the injured party.
I did receive this letter below finally from Vodacom on 19 May 2025 after insisting on a written response. But apart from confirming the account was paid in full (why was I reported?) there was no explanation nor apology.
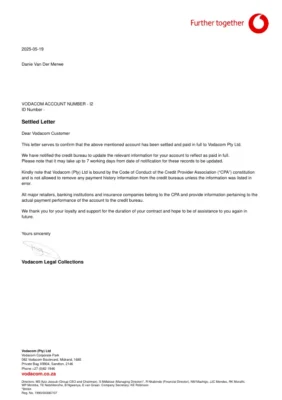
The whole point was that the credit bureaus STILL showed I had not paid my account for 3 months, and I did not even know why. The banks showed me that they can see very far back on one’s credit history, as well as a lot more information from 20+ years ago. And believe me, this can cost you real money! If you want an overdraft, or a mortgage to buy a house or do building alterations, or to buy a new car, etc, the bank determines an interest rate based on their risk. Just an extra quarter of a percent over a few years will cost you a lot (it compounds, too). This is why it is essential to clear your name or otherwise take accountability for your financial conduct.
Therefore, the same day, on 19 May 2025 at 16:53, I wrote back to Vodacom and stated my reasons clearly (and in bold) why I found the letter unacceptable, and giving them notice that I would start escalations on my side if I received no satisfactory response by the 23rd May 2025. Here is an excerpt of that response, as well as my follow-up notice of lodgement at the Ombud after I was ignored by Vodacom:
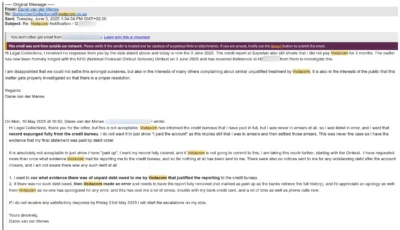
And so I lodged my case with the NFO on 3 June 2025.
“The primary purpose of the NFO is to resolve consumer complaints against financial service providers. The financial service providers within the NFO’s jurisdiction are those provided by our Participants, who comprise banks; Credit Providers; Short-Term Insurers (Non-Life Insurance); Long-Term Insurers (Life Insurance)”.
I can say that the NFO was very professional and responded with acknowledgements and follow-ups. They gave both parties two opportunities, as I recall, to respond. The final outcome from the NFO did achieve two goals:
1. The credit record regarding Vodacom was completely expunged from my record (including my 15 years of prior payments, unfortunately).
2. I did find out finally what I had “owed” Vodacom.
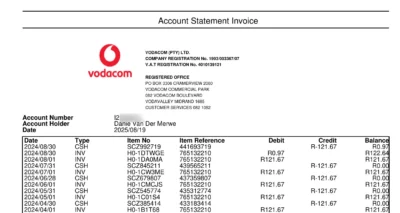
Vodacom did include a record to the NFO of all my transactions dating back to 2010 (468 entries in all) as well the outstanding balance. The outstanding balance was 97c. No, I kid you not, and you can see an extract of the final entries below. It seems this 97c entry was added on the very day the account was closed i.e. 30 August 2024. I have no idea what it is actually for, and it being added on the last day, I would not have known about it when the last statement reached me at the end of July 2024. With the account closed, I also had no way of seeing there was such an amount added.
I do also need to add that since the end of August 2024 when the account was closed, apart from me having no login access, I was sent not a single e-mail nor SMS by Vodacom to inform me there was still 97c outstanding on my account. All the phone calls and follow ups and escalations on my side have cost me far more than 97c to get this sorted out.
What was not sorted out by the NFO, was that I got no apology from Vodacom nor did I know what the 97c was actually for. In Vodacom’s defence around the apology (or call it reasoning) was they stated to the NFO the following response after the NFO had furthered the investigation:
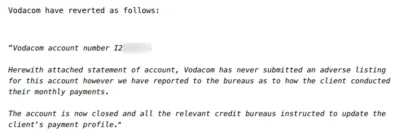
So let me try to interpret what Vodacom was saying here: We never explicitly reported this customer for an adverse listing, but we merely report how the customer paid/did not pay their account. “It’s not us, it’s the system”. I responded to the NFO then that, seeing there was no apology, and I find it unacceptable that “behaviour” gets reported when there was no notice sent to the customer, and the customer was not even aware of this “conduct”, I reserve the right then to tell my story publicly in the interests of other Vodacom customers that have complained about similar issues.
Clearly there is some system (IT or organisational) issue at Vodacom that needs revision (call it quality control). It is appalling that custonmers can have their records ruined by some automated system with no oversight, and that they have to go to such lengths to rectify it (without even an apology). I know I’m not the first and only customer to have this problem, but the whole reporting without notice to Experian and other credit bureaus, is just not acceptable. The fact too that a credit bureau can just completely ignore a dispute lodged formally with them is just as shocking. The credit bureau is the one which actually publishes the report.
I am just thankful that my new bank made me aware of this, and was prepared to accept my side of the events.
So some lessons learnt here:
- Make sure you do verify after an account closure and get some proof of settlement (recorded call, e-mail, print out).
- Record all your phone calls, keep e-mail and SMSs from corporates especially if they contract over the phone.
- Check your credit record with Experian or other credit bureau every few months – it costs nothing.
- If you have tried unsuccessfully to settle a dispute then lodge it with an Ombud to take it up for you. I have used Ombuds a few times and every time I have won my cases against big corporates.
- Keep your cool, record everything, and stand your ground. Don’t be bullied by big corporates (I could tell a funny story of how I beat a cellular company years ago by using their own bureacracy against them, but it would be another whole post).
- Having to log in and get your monthly statement is a major pain, even bigger if you only work on a phone, but try set todo reminders monthly to ensure yoiu did download and save them. I’d like to see the law requiring an actual staement being needed to be attached to an e-mail (encrypted if needed) and only that is considered as “sending of a statement”.